A return to go-go inflation is lousy on the wallet but may be good for your tax refund.
The U.S. inflation rate hit 8.5% in March over the past 12 months – the largest 12-month increase since December 1981 when “Falcon Crest” debuted on Friday nights on CBS right after “Dallas.”
Gas prices alone rose 48% in March, contributing to the unsteady feeling that consumers have about their wealth and the health of the U.S. economy.
Oddly enough, the IRS has a form relating to an inflation play for savings that some late filers still have time to consider.
We’re edging closer to the April 18 deadline for filing federal income tax returns, Michigan returns and city of Detroit and other communities.
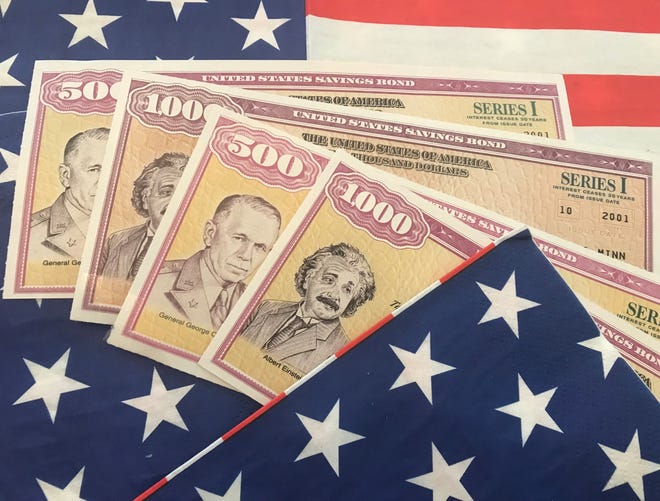
While many people never heard of this tax tip, taxpayers can file what’s called Form 8888 to use at least part of their federal income tax refund to directly buy inflation-indexed savings bonds when they’re filing their federal tax returns.
True, until inflation started heating up, many people heard more about bitcoin than I Bonds.
Now, though, I Bonds are paying the highest inflation-adjusted rates since they were introduced in September 1998, which makes sense since consumer prices haven’t skyrocketed this much in roughly 40 years.
Savers began to do a serious double take in November when the annualized rate for new inflation-indexed savings bonds hit 7.12% for a six-month period.
►2022 tax guide:Key dates for filing and extensions, claiming credits and planning for refunds
How does an I Bond look next to a CD?
I Bond rates are far higher than the rates savers are getting on bank deposits.
The average one-year certificate of deposit is yielding 0.22% now, up only slightly compared with a mere 0.18% a year ago, according to Bankrate.com.
Savers who shop around can find top-yielding CDs at 1.25% now, according to Bankrate.com, compared with 0.67% a year ago.
I Bond rates aren’t simple, unfortunately, to understand.
That 7.12% annualized I Bond rate applies to the first six months after you bought I Bonds from Nov. 1, 2021, through April 30, 2022.
The high rate ultimately kicks in for I Bonds bought before Nov. 1, 2021, too. When the high 7.12% annualized rate would start varies on the month when you bought the bond. Again, it applies to a six-month window.
Sales for I Bonds have been hitting records. I Bond purchases reached $1.31 billion in November, $3.04 billion in December, $3.538 billion in January, $1.246 billion in February, and $1.378 billion in March, according to the Government Monthly Statement of Public Debt.
By contrast early last year, savers bought but $249 million in I Bonds in January 2021.
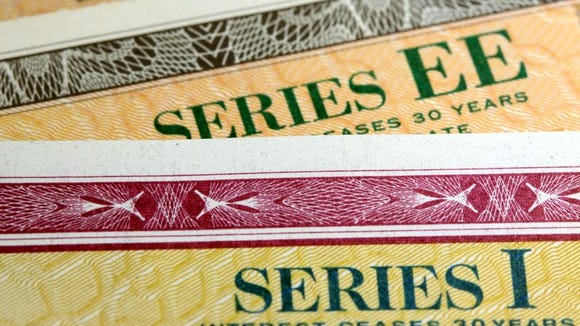
I Bonds outsold Series EE savings bonds for the past five months by $100 to $1, according to Pederson. (The Series EE rate is but 0.1% for bonds bought from November through April 30; the bonds, though, are guaranteed to double in value if kept for 20 years so longer-term savers would earn a considerably higher rate.)
And rates are likely to go higher – creating even more frenzy for the I Bond story.
The latest inflation data allows for estimates about where rates for I Bonds will go in the future.
The annualized rate, which will be announced on May 1, is likely to be around 9.6% for a six-month period, according to Daniel Pederson, a Monroe, Michigan-based savings bond expert and founder of www.BondHelper.com.
Again, the upcoming I Bond rate would apply for six months for purchases beginning May 1. Don’t worry if you bought I Bonds previously, though, as you do get the new higher rate for a six-month period as well.
►2022 taxes:Refunds are higher thanks to Child Tax Credit, third stimulus check
►Tax deadline this year:Not ready for the April 18 tax deadline? Here’s how to file an extension.
►Record inflation:After a string of 40-year highs, will inflation slow down? Some economists think so.
How do I Bonds and tax refunds mix?
Believe it or not, taxpayers can allocate tax refund money to I Bonds if they use Form 8888. The instructions note that you are able to use at least part of your refund to buy up to $5,000 in paper or electronic I Bonds. (You cannot use Form 8888 if you’re trying to claim refund money via an “Injured Spouse Allocation.”)
If you have a $6,000 refund, for example, you’ll be able to buy only $5,000 in I Bonds and can directly deposit the rest elsewhere.
The same form also allows you to directly deposit a refund or part of it into either two or three accounts at a bank or other financial institution, including a mutual fund or brokerage account.
When Pederson electronically filed his tax return in March, he included Form 8888 to use some of his refund money to buy I Bonds.
“I still haven’t gotten the paper bonds yet,” Pederson said.
When he gets them, he’s going to pay close attention to the issue date to see what rate first kicks in. He maintains that given when he filed his return he should be getting the rate before the new rate hits May 1.
Not surprisingly, his tax professional did not see a flood of taxpayers using Form 8888 to buy I Bonds.
What issue date would you get?
The Internal Revenue Service notes that I Bonds won’t be issued until the agency completes processing your tax return.
The return process needs to be completed, the IRS said, in case there are changes in the actual refund amount.
The instructions for Form 8888 point out that I Bonds wouldn’t be issued, for example, if your refund is decreased because of a math error. And I Bonds wouldn’t be issued if your federal income tax refund is offset for any reason to cover an unpaid debt owed to state and federal agencies and then the refund ends up being sent to you in the form of a check.
The amount you buy in I Bonds via your tax refund must be in multiples of $50 or the request will be rejected. A bond request that’s for $438 would be rejected. You’d have to request $400 in I Bonds in this example and take the remaining $38 via direct deposit elsewhere.
What’s the big deal about buying bonds with a tax refund?
Dollar limits exist for I Bond purchases each year. The tax refund route enables you to buy up to $5,000 in I Bonds on top of other limits.
The annual limit is $10,000 in I Bonds that can be bought each calendar year per person. You buy savings bonds at www.TreasuryDirect.gov and hold them in an online account.
You can no longer buy savings bonds in person at banks.
Paper I Bonds are only available if you allocate all or part of your income tax refund to I Bonds on Form 8888 when you file your tax return.
►I Bonds:What’s not to love? The US savings bond with inflation protection gets ignored
►Profit during inflation?:These five tips could help investors beat rising prices
What about older I Bonds?
The last thing anyone should do is cash out of I Bonds bought 15 years ago or so to buy these newer bonds.
The reason? Some older bonds still are paying far more than the new ones.
I Bonds bought before Nov. 1, 2001, for example, are the best of the bunch and have a fixed rate of 3% or higher. The highest fixed rate was 3.6% for I Bonds issued from May 2000 through October 2000.
Savers holding older I Bonds with a fixed rate of 3% or higher would see an annualized rate of around 12.6% or more once that estimated May 1 rate kicks in.
Savers who bought in future years saw that fixed rate drop a bit to around 2% or higher for I Bonds bought after late 2001 but before Nov. 1, 2002. Any inflation adjustment is added to that fixed rate.
As of November 2002, we were looking at a fixed rate of 1% or higher for I Bonds bought before May 1, 2008.
I Bonds bought after May 1, 2008, end up with much smaller fixed rates. Depending on when you bought the bond, the smaller fixed rates will vary. The fixed rate on I Bonds consistently has been 0% for bonds bought from May 2020.
If inflation cools in the next year or two, the inflation-adjusted rate would be lower but still added onto that 0% fixed rate.
Buy now if you can or later
One inflation-focused strategy suggests buying I Bonds before April 30 to lock in an exceptionally strong rate over a one-year time frame.
The annualized rate of 7.12% for the first six months would start in April and run six months through September for bonds bought before April 30.
Then the same bonds would pay an estimated annualized rate of 9.6% from October through March.
Following this strategy, Pederson said, the average rate would end up being 8.36% over the 12 months.
It’s important to know that you cannot cash I Bonds until you’ve held them for at least 12 months. And you’d lose the most recent three months of interest if you redeem the I Bonds within the first five years.
Even if you had to sell the I Bonds a bit more than a year after buying them, Pederson said, you’d be earning close to 5.96% after the penalty if you buy before the rate changes on May 1. (As April 30 is a Saturday, you’d want to buy the I Bonds a few days beforehand to make sure to get that April rate.)
Inflation could remain steady in the months ahead, given Russia’s war against Ukraine and supply chain disruptions. But inflation could also cool down some, as the Federal Reserve moves to boost rates and Washington makes some moves to bring down the price of gas.
What’s known now is the rate that’s good through April 30 and we have a decent estimate for the six-month range after that.
I Bonds make sense for savers who want to snag significantly higher rates than if they parked that money in a one-year certificate of deposit.
ContactSusan Tompor via [email protected]. Follow her on Twitter@tompor. To subscribe, please go to freep.com/specialoffer. Read more on business and sign up for our business newsletter.
About the Author

