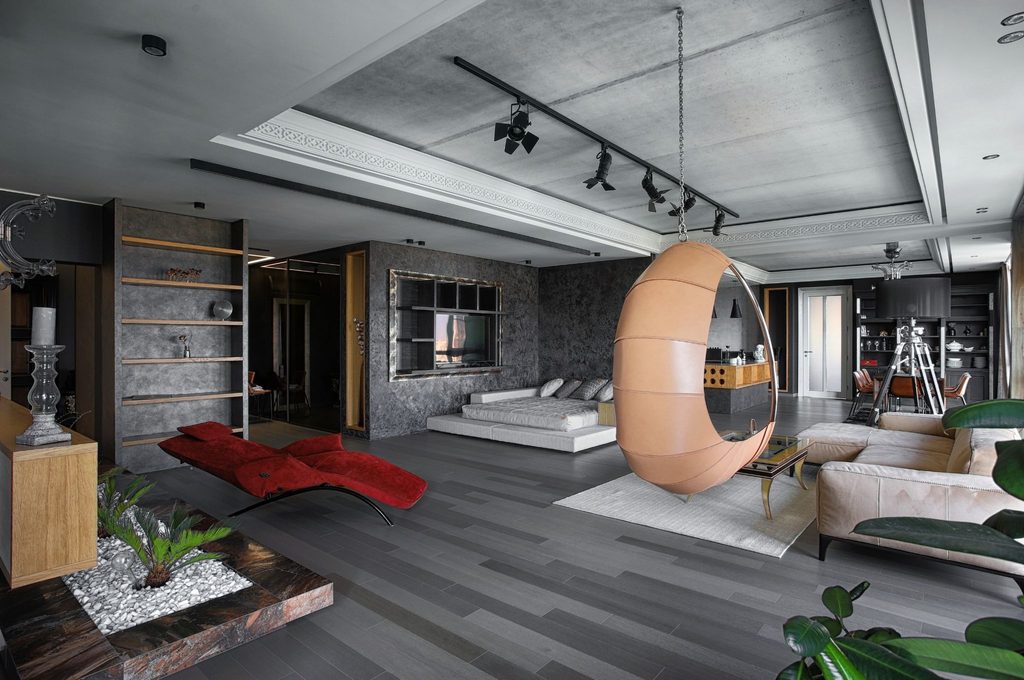
Collecting the keys to your new Housing & Development Board (HDB) flat or private condominium marks an extraordinary milestone. However, stepping across the threshold reveals a blank canvas that requires significant capital to transform into a comfortable sanctuary. From custom carpentry and hack work to electrical rewiring and premium flooring, interior works demand a substantial financial investment. Few homeowners possess the liquid cash needed to fund an entire overhaul out of pocket without draining their emergency savings. A tailored renovation loan in Singapore bridges this gap, allowing you to build your dream living space while keeping your daily cash flow intact. Evaluating your options before signing a contractor agreement guarantees a stress-free transformation.
Calculating the True Scope: Differentiating Fixed Structure from Furnishings
Before applying for financing, clearly distinguish between structural renovation costs, typically covered by institutional loans, such as carpentry, flooring, and electrical rewiring, and decorative furnishings. Most financial facilities strictly exclude non-structural items like freestanding furniture, appliances, and curtains. Identifying these boundaries upfront helps prevent funding gaps, as these loans are specifically designed for core construction elements rather than loose home fittings.
Beyond material costs, proactively budget for hidden expenses like municipal disposal fees, interior design drafting, site protection, and post-construction cleaning. Categorising these secondary costs is essential to avoid mid-project funding shortfalls. By isolating core structural expenses from these incidental project fees, you can maximise your renovation loan’s utility while preserving your personal cash reserves for those essential appliances and loose furniture items.
Bank Constraints vs Flexible Lenders: Choosing Your Financial Partner
When seeking capital for home improvement, homeowners choose between traditional commercial banks and legal alternative financial institutions. Traditional retail banks enforce rigid borrowing limits, typically capping facility amounts at six times your monthly salary or a maximum ceiling of $30,000.
Furthermore, commercial banks impose restrictive disbursement processes, paying funds directly to contractors via cashier’s orders only after verifying strict quotation line items. If your preferred interior firm requires rapid milestone payments or your project incurs unexpected variation order (VO) costs, bank delays can stall work progress completely.
Conversely, partnering with a legal, regulated, licensed moneylender provides a fast, adaptable solution. Regulated alternative financial providers evaluate your immediate income stability and repayment capability rather than enforcing rigid quotation categories. Working with a legal, licensed moneylender ensures fast approvals and direct cash disbursement, giving you complete flexibility to settle unexpected contractor variation orders, buy raw materials directly, or purchase loose home furnishings without delay.
Balancing Repayment Tenures: Protecting Your Post-Move Monthly Budget
Selecting the right repayment tenure directly dictates your monthly household budget. Spreading your loan repayments across a longer period lowers your mandatory monthly instalment, keeping your day-to-day living expenses comfortable as you settle into your new home.
However, extending your tenure incurs higher total interest over time. Before finalising your financing contract, evaluate your combined household cash flow carefully. Ensure that your monthly home improvement instalment, when combined with your ongoing property mortgage, utilities, and grocery bills, leaves a healthy cash buffer for unforeseen life events.
Proactive Strategies for Managing Interior Contractors Smoothly
Securing your funding represents only half the battle; managing your renovation budget requires ongoing vigilance to prevent cost overruns. Adopting a disciplined project management approach keeps your contractor accountable and protects your wallet. To begin with, secure multiple itemised quotes to compare detailed line-item costings from at least three accredited interior firms before signing any agreements. Additionally, establish a contingency cushion by allocating 10% to 15% of your total budget specifically for unexpected variation orders and structural repairs.
Furthermore, enforce progress-based payments by structuring payment schedules around verified project milestones rather than paying large upfront deposits. You should also verify material specifications directly by inspecting tile batches, laminate grades, and countertop materials on-site before installation begins. Following these practical steps ensures that your project finishes on schedule, within scope, and completely inside your budget limits.
Bringing Your Vision to Life
Upgrading your home should feel like an exciting adventure rather than a source of financial stress. By defining your project scope clearly, choosing a flexible financial partner, selecting a balanced loan tenure, and managing your contractor strictly, you protect your household cash flow. Strategic planning allows you to create a beautiful, modern living space that brings joy to your family for years to come.
Frequently Asked Questions
What is the maximum amount I can borrow for a home upgrade in Singapore?
Traditional bank facilities typically cap borrowing at six times your monthly salary or $30,000. Regulated alternative lenders evaluate your overall monthly income and offer flexible unsecured personal loans to cover additional expenses.
Can I use a renovation loan to purchase home appliances and furniture?
Standard bank facilities restrict usage strictly to structural renovation works like carpentry and tiling. However, taking an unsecured personal loan gives you complete freedom to purchase appliances, loose furniture, and decor.
How quickly do alternative lenders disburse approved funds?
Regulated alternative financial institutions in Singapore process applications rapidly, frequently disbursing approved funds on the same day when you apply using Singpass MyInfo.
Transform your flat into a dream home with fast, flexible, and transparent financing tailored to your budget. Contact 118 Credit to learn more.
About the Author


